Key Takeaways:
- As many as 46 states require TPA licensing or regulatory filings before you can administer plans or process claims on behalf of others.
- The global insurance TPA market grew to $404.27 billion in 2026 at an 8.7% CAGR, driven by employer adoption of self-funded health plans.
- Early niche specialization (health benefits, retirement plans, or workers’ compensation) directly shapes your licensing path, technology requirements, and fee structure.
- Errors and Omissions insurance and a fiduciary liability policy are non-negotiable at launch; Oregon requires minimum E&O coverage of $500,000 per occurrence.
- ERISA fiduciary exposure can attach to your TPA at formation if you control claims processing and your own compensation simultaneously. Structure service agreements before you sign your first client.
- Claims administration accounts for 40.76% of TPA service revenue, making it the revenue anchor you should build your initial business model around.
Starting a TPA from scratch means building something that sits at the intersection of employers, carriers, and the people those plans actually cover. Before you file an application or incorporate an entity, it helps to understand exactly what the work looks like day to day and who you’re accountable to.
What a TPA Actually Does
A TPA handles benefits administration, claims processing, and regulatory reporting on behalf of plan sponsors and insurance carriers, without carrying the underlying insurance risk. The work is relational and deadline-driven.
The workflows TPAs handle
On any given day, a TPA’s team is handling FNOL intake, routing claims to adjusters or reviewing them in-house, tracking reserves, issuing payment authorizations to financial partners, generating bordereaux for carriers, and fielding participant inquiries. Every link in the reporting chain, from the insured through the TPA to the carrier, carries hard deadlines. Miss a filing window or submit an inaccurate report and you’ll damage the carrier relationship that keeps your book alive. The claims outsourcing trend is picking up speed: carriers are handing off claims administration in growing numbers to cut overhead, which opens a direct pipeline of work for new TPAs who can prove they’ll manage it properly.
Where TPAs fit in the insurance ecosystem
TPAs sit between plan sponsors (employers, self-insured groups, captives) and the carriers or reinsurers who ultimately backstop the risk. According to market analysis from Mordor Intelligence, claims administration holds 40.76% of TPA service revenue, the largest single line. Straits Research notes the insurance TPA market is structurally fragmented, with openings for regional and specialty entrants. And according to Research and Markets, sustained self-funded plan penetration among mid-market employers is the main demand signal for new TPA formation.
Types of TPAs and Which Niche Fits Your Business
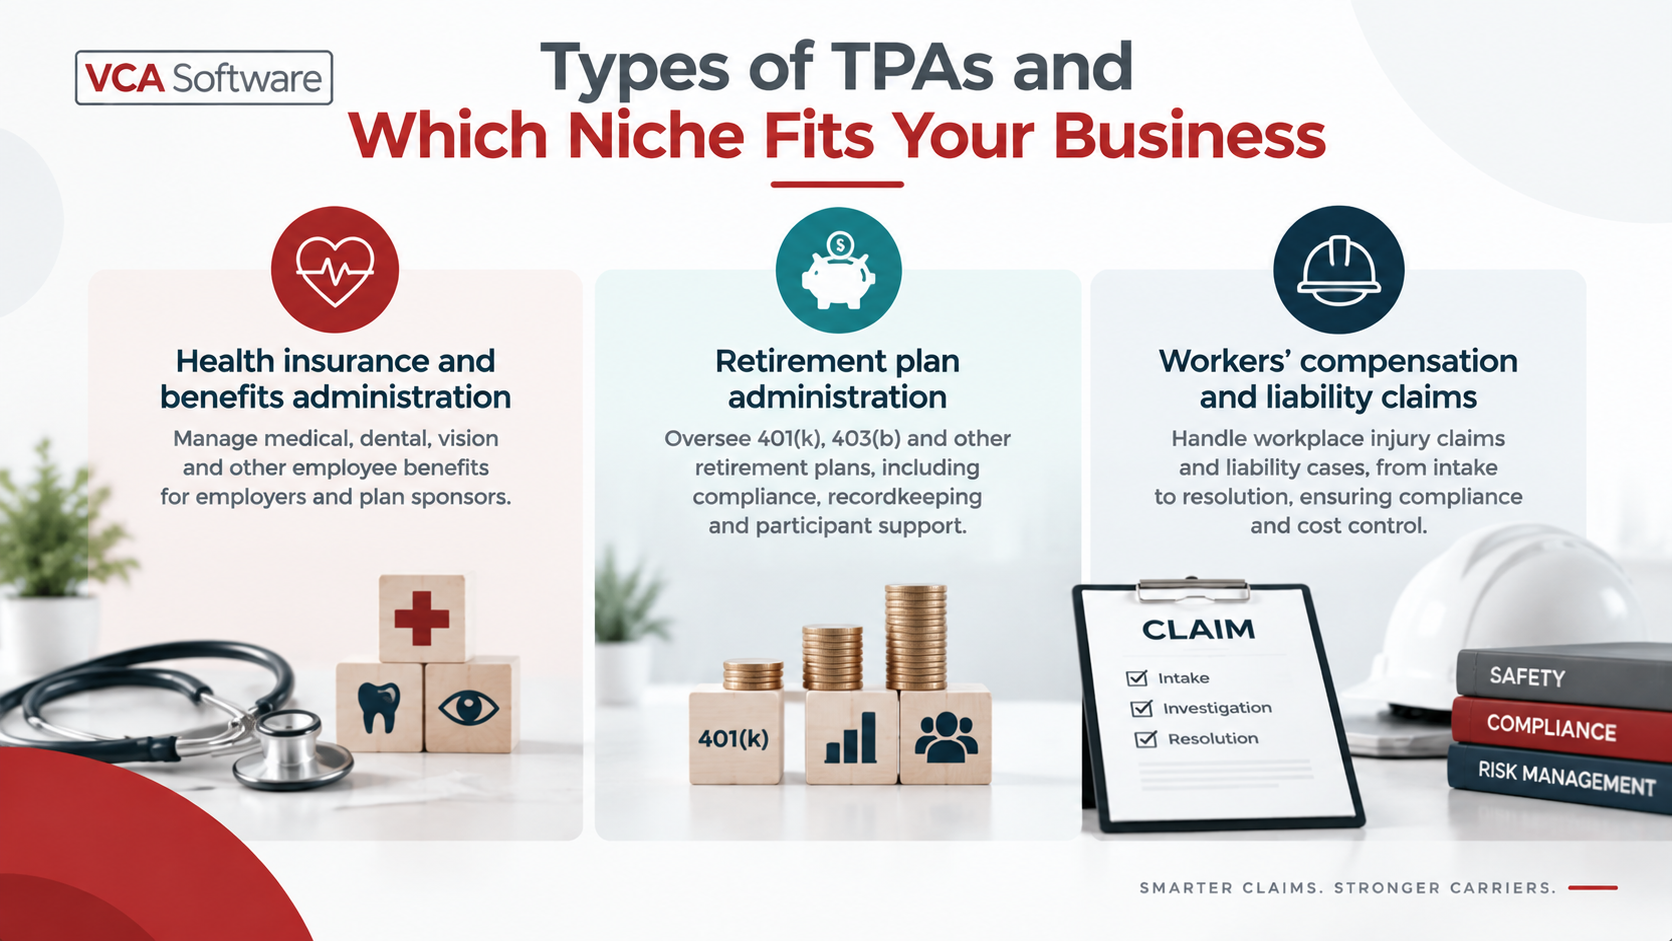
Picking a niche early is more than a marketing call. It shapes which licenses you’ll need, which technology you’ll buy, and what your hiring plan looks like. Research consistently shows that early specialization drives client acquisition and cost-effectiveness far more than trying to serve every plan type from launch day.
Health insurance and benefits administration
Health and life administration led the field with 51.27% of TPA market share in 2025, according to Spherical Insights. The opportunity is genuine: the Kaiser Family Foundation’s 2025 Employer Health Benefits Survey found that 67% of covered workers were enrolled in self-funded arrangements, including 27% at firms with 10 to 199 employees, figures detailed in the KFF survey. Health TPAs must manage ERISA, ACA reporting, HIPAA compliance, and stop-loss coordination all at once. The per-employee-per-month fee model is the standard here, and Business Associate Agreements (BAAs) with every data-handling partner are mandatory before you onboard a single plan.
Retirement plan administration
| Dimension | Retirement TPA |
|---|---|
| Primary regulator | DOL / IRS |
| Compliance obligations | ERISA, Form 5500 filing, discrimination testing |
| Client relationship | Plan sponsor (employer) |
| Common fee model | Flat annual fee or per-participant |
| Licensing requirement | Generally no state TPA license; may require securities registration |
| Technology need | Recordkeeping platform, participant portal |
Startup costs for a retirement TPA skew toward legal and technology infrastructure: entity formation, recordkeeping software, ERISA counsel retainer, and professional liability coverage. Depending on the services offered, some firms require registration as an investment adviser.
Workers’ compensation and liability claims
Workers’ comp TPAs work directly inside the claims file, handling FNOL intake, adjuster assignment, medical bill review, reserve setting, litigation management, and state regulatory filings. It’s a claims-intensive niche that demands adjusting expertise either on staff or through contracted IAs. Catastrophe volumes, social inflation, and carrier outsourcing have all pushed demand for capable third-party handlers, as detailed in market disruption creating opportunity for IAs and TPAs. The Business Research Company’s 2026 global market report identifies AI-driven claims automation and self-insured employer growth as the main structural drivers through 2030. Budget roughly $150,000 to $300,000 in pre-launch capital for technology, insurance, and operating reserves; the exact figure depends on state bond requirements, staffing, and software contracts.
Licensing Requirements by State
TPA licensing in the United States is regulated at the state level, and requirements differ materially across jurisdictions. This section reflects general principles only; it’s not legal advice for your specific state. Consult a licensed attorney before filing any applications.
Who needs a TPA license
As many as 46 states require licensing or regulatory filings to operate as a TPA, as shown in the NAIC’s Spring 2025 licensure and bond requirements chart. Some states exempt certain plan types. Retirement-only administrators often fall outside insurance department jurisdiction altogether. The most thorough reference for state-by-state statutory variations is the SPBA’s 2025 state licensing survey, published by the Society of Professional Benefit Administrators.
Requirements and application process
Most state applications require financial statements, a business plan, sample client contracts, and background checks for principals and key personnel. Some states require a fidelity or surety bond: Texas requires a bond of at least $10,000 or up to $500,000, depending on funds handled. States vary dramatically on processing time. New York’s Workers’ Compensation Board, Oregon’s Division of Financial Regulation, Connecticut’s Insurance Department, North Carolina’s DOI, and Washington’s L&I all publish jurisdiction-specific guides. Build several months of buffer into your launch timeline. Some states approve in weeks, others take four to six months.
Renewal, reporting, and ongoing compliance
Most state licenses renew annually or biennially. Renewal typically calls for updated financial statements, E&O insurance certificates, and confirmation that your principals still satisfy fitness requirements. Oregon, as one representative example, requires E&O coverage of at least $500,000 per occurrence.
Building Your TPA From the Ground Up
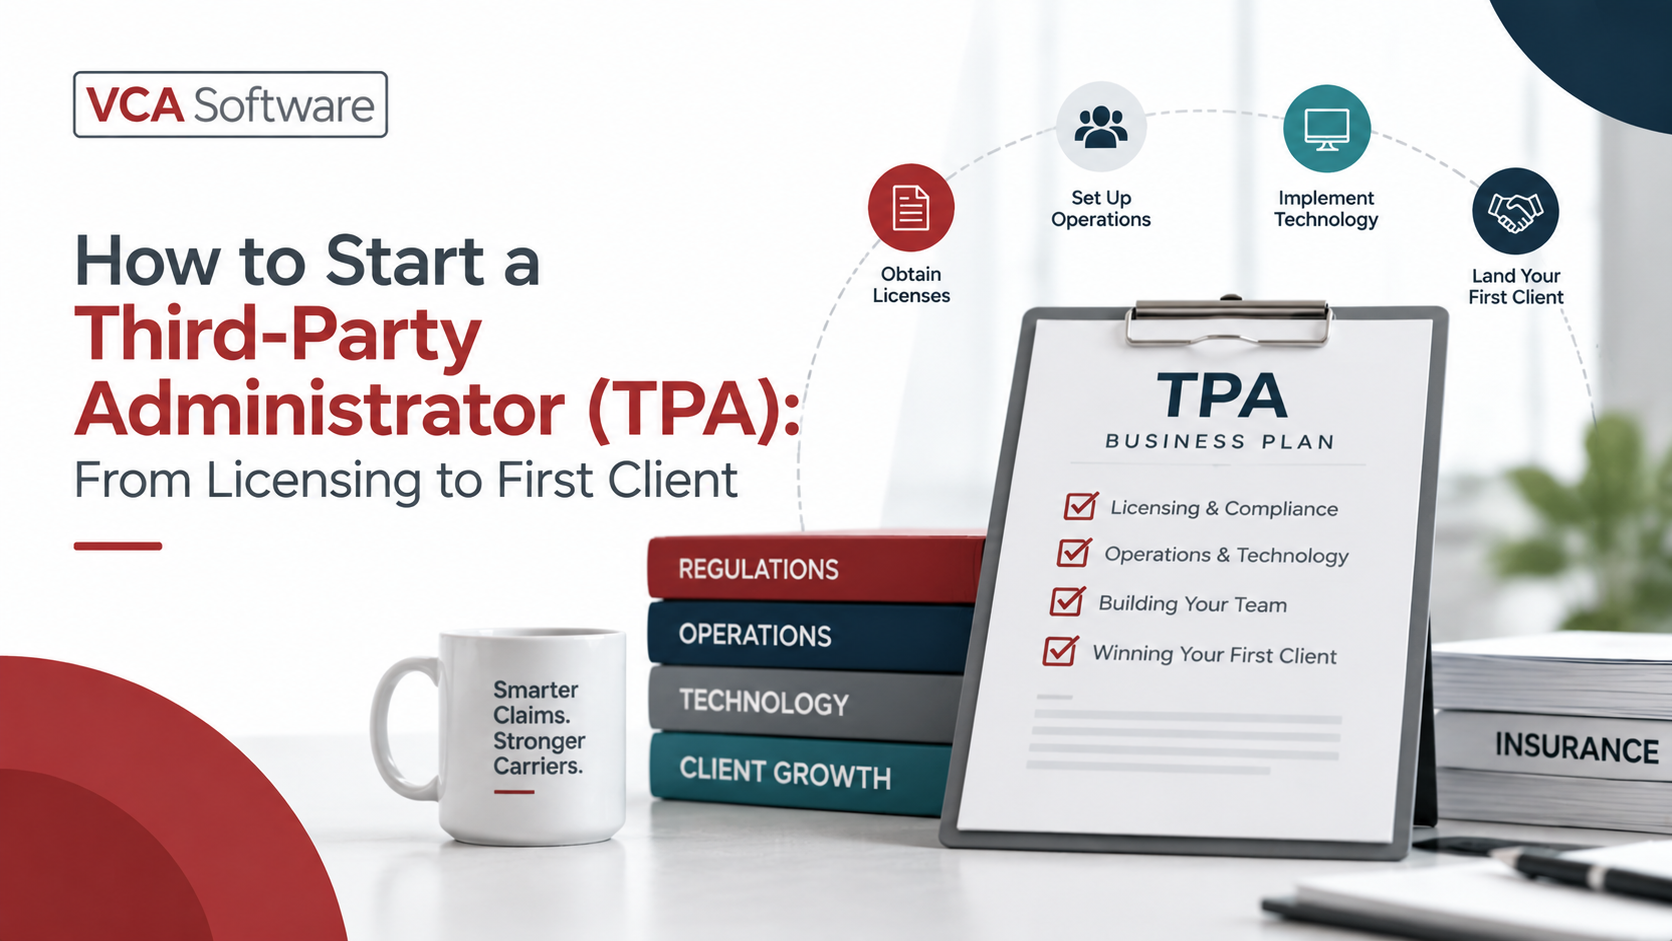
Before you can administer a single plan, three infrastructure layers must be in place: legal, insurance, and technology.
Choosing your niche and target market
Entity registration (LLC or corporation, depending on state requirements) and commercial licensing come first. Then map your federal compliance obligations: health-focused TPAs must address ERISA plan fiduciary duties, HIPAA and ACA frameworks, and execute BAAs before handling any protected health information. If your fee arrangement gives you control over your own compensation through shared savings or similar structures, the Sixth Circuit’s May 2025 ruling in Tiara Yachts, Inc. v. Blue Cross Blue Shield of Michigan (which held that such arrangements can trigger ERISA fiduciary status) means your service agreement language needs legal review before it’s signed, not after.
Setting up operations and technology
Technology is where many founders underestimate the build effort. A TPA platform needs to handle claims adjudication, participant enrollment, data reporting for carrier and regulatory filings, and document management, all with a full audit trail. Claims management APIs are the connective tissue between your system and financial, provider, and carrier partners; without them, your team ends up copying data between platforms manually. The build vs. buy decision almost always favors buying a purpose-built platform for a startup TPA. Custom development costs and maintenance cycles will outpace subscription fees for years. When selecting claims management software, evaluate for claims adjudication depth, feature coverage for your niche, and SOC 2 compliance; an integrated claims management system reduces data fragmentation that causes compliance errors. Workers’ comp TPAs have different system requirements than retirement administrators, so who your client is drives what has to go in. For additional context on the technology stack for IA firms, the same principles apply to TPA launch decisions. Budget for the TPA software market pricing range; mid-market platforms typically start between $100 and $500 per month per user.
Hiring and staffing your first teams
Experienced adjusters and benefits specialists are hard to find. The insurance industry faces a talent crunch. BLS data cited by claims talent planning research suggests the industry could lose 400,000 workers by 2026. Lead with technology as a recruiting asset; modern tools attract candidates who want streamlined workflows, not paper files. Smart claims technology also lets a lean team handle more volume without burning out, which matters when your first hires are covering multiple roles simultaneously.
How TPAs Make Money
The TPA service market is projected to grow to $14.1 billion by 2035 at a 3.9% CAGR, per the Future Market Insights forecast, up from $9.6 billion in 2025. TPA service revenue forecasts reflect consistent demand for third-party administration across health, workers’ comp, and specialty lines.
Fee structures and pricing models
| Fee model | Common in | Typical structure |
|---|---|---|
| Per-employee-per-month (PEPM) | Health benefits | $15 to $50 PEPM |
| Per-claim fee | Workers’ comp, liability | $50 to $250 per claim |
| Percentage of premium | Workers’ comp | 5% to 15% of total premium |
| Flat annual fee | Retirement plans | Fixed by plan size |
| Hourly / project | Complex cases | Negotiated |
No single model is universally superior. The trade-off is predictability versus scalability: PEPM gives you stable forecasting but caps upside when claim volumes spike; per-claim models reward streamlining but create revenue volatility. Tracking the right metrics (including cost per claim, cycle time, and client retention rate) from month one tells you whether your pricing model is covering actual operational costs.
Revenue beyond administration fees
Carrier volume credits, investment income on fiduciary accounts, and add-on services like analytics reporting are revenue lines that generally develop after your first 12 to 18 months. Claims management dashboards that surface real-time performance data let you show clients measurable value and justify premium pricing. Early client acquisition runs through broker and carrier relationships, brokers refer self-funded employers needing administrative support, while carriers refer groups that have outgrown their internal capacity. Building those relationships before launch beats cold outreach after the fact. Faster claims processing is also a genuine selling point; clients paying a PEPM fee want to see their claims moving, not sitting idle.
Staying Compliant After Launch
Compliance doesn’t end when your license arrives. It’s an ongoing operational function that runs parallel to everything else you do.
Annual reports and regulatory filings
Most states require annual financial reports, renewed E&O certificates, and updated principal disclosures. Let a renewal date slip and your license can lapse while clients’ plans keep running, a serious regulatory exposure. Strong claims operations infrastructure keeps audit trails current automatically, which is exactly what regulators look at during examinations.
Common post-licensure transactions
Adding a new state, expanding service lines, or changing ownership typically triggers a regulatory filing. Some jurisdictions treat these as material changes that need prior approval. Requirements vary by state and plan type, so get qualified legal counsel for any jurisdiction-specific guidance.
Managing errors and audit exposure
Your E&O policy covers claims errors and process failures, but documentation is your first line of defense. Compliance frameworks built around claims systems – with immutable audit logs, documented decision rationale, and version-controlled correspondence – are what protect you when a dispute escalates. Claims handling best practices that include prompt acknowledgment timelines, written coverage determinations, and reserve documentation cut both your E&O exposure and the probability of a bad-faith allegation.
Common Mistakes When Starting a TPA
The most common mistakes are operational, not legal. Founders underestimate how quickly an inefficient claims system compounds: slow cycle times erode client confidence, generate carrier complaints, and burn out staff – all in the same downward spiral. Undercapitalizing technology relative to headcount is the second pattern. Hiring people before buying the system that makes them productive costs more in the long run. And claims leakage – money that escapes through overpayments, missed recoveries, and process gaps, is nearly invisible without audit-ready reporting. Build that reporting before you need it, not after your first client audit.
How VCA Software Supports New TPA Operations
Starting a TPA means building a claims operation from the ground up, and the technology you choose at launch shapes how the work runs from day one. VCA Software is a purpose-built claims management platform used by TPAs, independent adjusting firms, carriers, captives, and self-insured entities across more than 15 countries. Unlike generic platforms adapted from sales or project-management tools, VCA’s platform is built around real claims workflows: FNOL intake, adjuster assignment, reserve tracking, bordereaux reporting, and carrier handoffs.
For new TPAs, a few things matter most. VCA’s integrated claims management system includes built-in Lloyd’s reporting capabilities, configurable audit trails, and API connectivity to financial and carrier systems, reducing the compliance exposure that catches new operators off guard. The platform can be up and running in as little as two to three weeks for new clients, and most file handlers are productive in under two hours of training. That short ramp time is a function of how the workflows are designed, not just the training program.
VCA Insights, the analytics module, surfaces real-time performance data – cost per claim, cycle time, reserve accuracy – that clients expect and regulators examine. Pricing starts in the mid-market range, making it accessible to a startup TPA without giving up the features you’d need to win carrier and broker confidence. If you’re still weighing your options, the best claims management software comparison covers how VCA stacks up against the broader market.
Conclusion
Starting a third-party administrator requires sequential decisions: pick your niche, map your state licensing requirements, build your legal and technology infrastructure, and price your services against real operational costs. The demand is there. Self-funded plan penetration continues to expand into the mid-market, and carriers are actively outsourcing administration to control overhead. What separates TPAs that grow from those that stall is usually operational quality: claims that move forward correctly, reports that land on time, and client relationships built on visibility rather than reassurances. Get the foundation right, and the business follows. This is general educational information; consult a licensed attorney and qualified financial advisor for advice specific to your jurisdiction and situation.