Key Takeaways:
- Claims software should deliver three measurable outcomes: shorter cycle times, compliance readiness, and lower loss adjustment expense, not a feature checklist.
- Automated FNOL intake, rules-based claim routing, and reserve tracking are the three workflow capabilities that move claims fastest.
- Cloud-native platforms deploy in 60 to 120 days; on-premises or custom builds typically run 12 to 24 months and cost significantly more.
- Claims systems should be evaluated by the people who work claims daily, not IT, because the right questions only come from inside a claim file.
- SOC 2 Type II certification is a non-negotiable security baseline; HIPAA applies wherever workers’ comp or health-adjacent lines are in scope.
- Subscription pricing scales better for mid-size carriers than upfront fees. Compare total cost including training and customization, not headline numbers alone.
Rate pressure has defined the P&C insurance market for years, and claims software for small and mid-size carriers now shapes combined ratio outcomes as much as IT budgets. Deloitte’s 2026 Global Insurance Outlook projects the U.S. P&C combined ratio will worsen to 99% this year, so every claim handled inefficiently lands directly on underwriting margins. This guide is for the carrier or TPA that wants an honest platform evaluation grounded in real workflow questions.
What Claims Software Needs to Do for Small and Mid-Size Carriers
Measure the outcomes first: faster cycle times, compliance readiness, and a demonstrable reduction in loss adjustment expense. Those are what you should be able to point to before you open a single demo.
The work before the software
A claim moves from the insured to the independent adjuster, from the IA to the TPA, from the TPA to the carrier, with reporting obligations, reserve decisions, and deadlines at every handoff. Claims satisfaction drives policyholder retention more than any other interaction, so your platform choice is a retention decision as much as an operations one. Start by mapping that work on paper, then let the software support it.
Where most carriers feel the friction
Duplicate data entry across disconnected systems. Manual reserve updates. FNOL submissions that sit in an email inbox until someone processes them. According to the insurance claims management solution market report, nearly 46% of small and mid-sized insurers cite high adoption costs as the barrier to better claims solutions, though the real cost is usually the friction they’re already paying every day. A 2025 study on AI adoption in insurance found that 90% of insurers are somewhere on the AI journey, but fewer than half have a model in production with measurable impact. Vendor AI claims deserve scrutiny against actual production outcomes, and independent reviews, like those compiled on mid-size claims platform comparisons, show how platforms perform under real operating conditions rather than in a demo.
Features That Actually Move Claims Forward
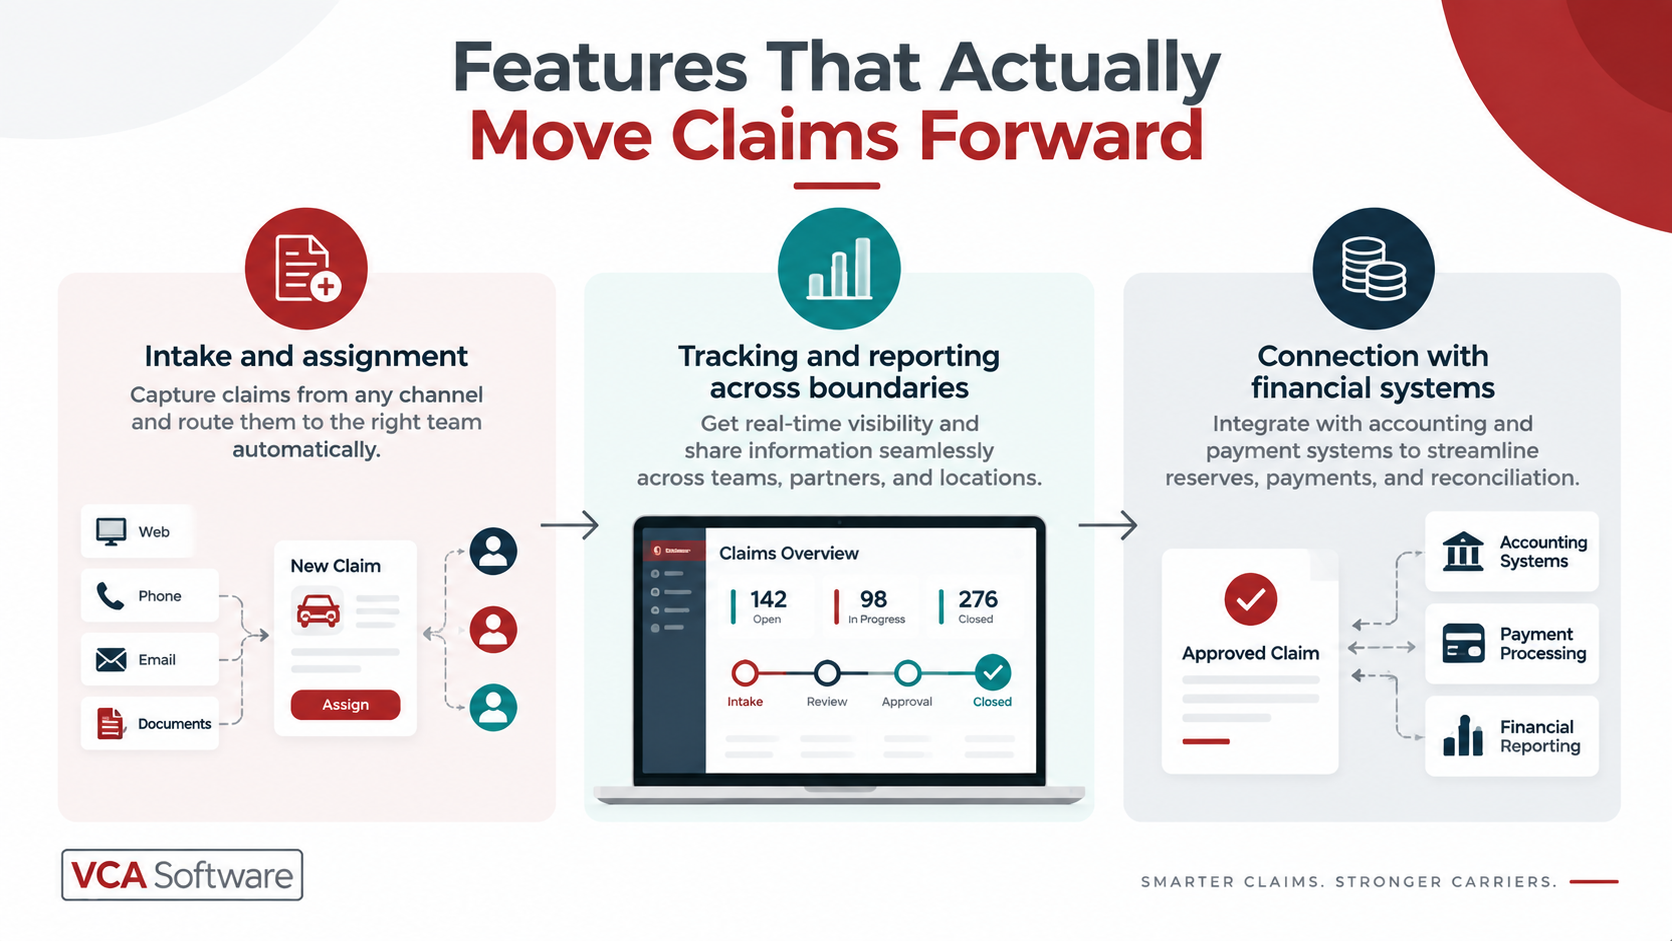
Correctness matters more than raw speed. Automating a broken workflow just moves you to the wrong outcome faster. The workflow capabilities worth prioritizing are the ones that move a claim forward accurately at every handoff: automated FNOL intake, intelligent claim assignment, and reserve and recovery tracking.
Intake and assignment
When a FNOL arrives, three things should trigger automatically: acknowledgment to the policyholder, structured data capture into the claim file, and initial routing to the right queue. Coverage verification, initial reserve setting, and anything touching liability judgment still need a human. FNOL automation handles the intake mechanics; the adjuster handles the decision. Rules-based routing by line of business, geography, or adjuster capacity is the recommended assignment method within automated workflows. According to the claims management software market analysis, platforms that process over 75% of FNOL submissions digitally reduce average claim cycle time by 31%. Per Research and Markets, the AI in claims processing market is growing at a 16.2% CAGR through 2030, so AI-assisted intake is becoming a baseline expectation rather than a premium add-on.
Tracking and reporting across boundaries
Effective claims operations require real-time visibility across all open files, not end-of-day batch reports. Look for platforms that surface adjuster workload, reserve adequacy, and deadline status in a single view. Bordereaux reporting, important for Lloyd’s-market carriers and MGAs, should be native rather than a custom export. Good claims handling practices depend on that data being current when a manager looks at it.
Connection with financial systems
Bi-directional APIs need to push reserve changes in real time to your accounting system, trigger payment workflows the moment a settlement is approved, and pull reconciliation confirmations back into the claim file. Third-party data providers, weather scoring services, fraud scoring feeds, and ISO ClaimSearch each add their own connection requirement. AI-driven claims automation performs best when those external data signals arrive at intake, before the file has already been routed somewhere.
Build vs. Buy: When to Configure, When to Code
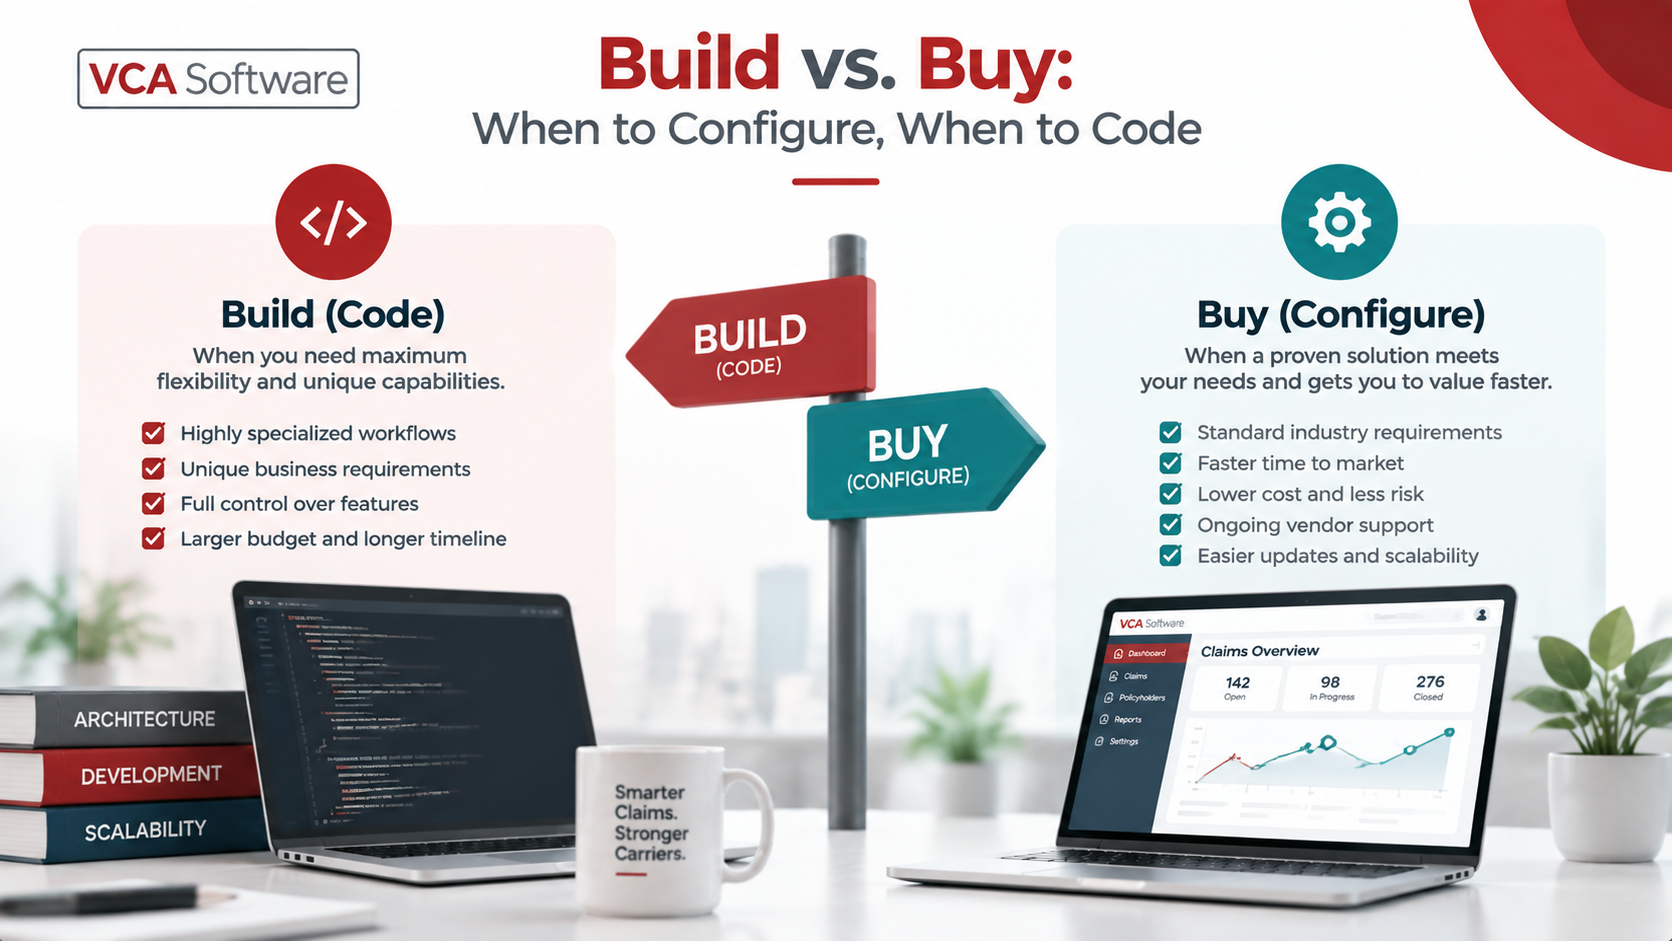
Carriers at this market size often misjudge the configurability-versus-customization spectrum. Building claims software in-house looks appealing (full control, no recurring fees), but the actual cost typically runs $500K to several million dollars before ongoing maintenance, which eats engineering capacity a small carrier doesn’t have to spare. Per the claims management software market sizing, the market is growing at over 10% annually in part because carriers are choosing purpose-built platforms over in-house builds. Platforms worth evaluating at this market size include BriteCore for regional carriers with complex policy admin needs, Five Sigma for a structured API-first handling approach, Snapsheet for digital-first claim experiences, and VCA Software’s modular approach for carriers and TPAs that need configurability without heavy customization overhead. AI insurance agents are now embedded in several mid-market platforms, so the more useful question isn’t whether a platform has AI, but where the AI actually lives in the workflow.
What in-house development really costs
Beyond initial build cost, factor in dedicated developers ($120K to $180K annually each), ongoing compliance updates when state regulations change, security patching, and the opportunity cost of engineers not working on core business problems. Most carriers that build in-house spend three to four times their original estimate by year two.
Why configurability matters (and where it can backfire)
Configure what matches the work and skip the rest. You can always add more later. Over-configuration is a real failure mode: too many statuses, too many custom fields, too many routing rules make the system harder for adjusters to use, not easier. The best platforms make it easy to start lean and grow the configuration deliberately.
Evaluating Software the Way Your Claims Team Works
Fit with actual workflows should drive evaluation more than feature completeness. Two pieces of information narrow platform selection faster than any RFP: the lines of business you handle and your current claim load volume. A TPA processing 2,000 workers’ comp claims annually has fundamentally different routing, reserve, and reporting needs than a surplus lines carrier managing 400 complex property files. Get those numbers before you shortlist. Cloud-native platforms generally deploy in 60 to 120 days; legacy overhauls can stretch to 18 months or longer, and how fast you go live is a legitimate measure of fit, not just a sales talking point.
Who should be in the room
Claims managers, senior adjusters, and the people who run bordereaux reporting should lead the evaluation, with IT weighing in on security architecture and API documentation. The questions that determine fit (“how do I split a reserve between two coverage parts?” or “can I see all open files by adjuster in one screen?”) come from people who work inside claim files every day, and an evaluation run by IT alone tends to miss most of the workflow gaps. Per insurance automation research, 90% of insurance executives acknowledge the need for human-AI collaboration, but only about 25% have acted on it, a gap that often starts with who’s in the room for technology decisions.
The questions IT alone will miss
How does the system handle a claim that touches three lines of business? What happens when an adjuster marks a file pending and another picks it up? Can a carrier-specific claims management dashboard be configured without a developer? These are claims questions before they’re technical ones.
How to demo without wasting time on feature lists
Ask the vendor to run a demo using your actual claim types. Start with FNOL, walk a file through reserve setting, then to payment trigger, then to a bordereaux pull. If they switch to a generic demo file mid-walkthrough, take note. Track the insurance KPIs that matter to your operation (cycle time, reserve accuracy, compliance status) and ask exactly where each one lives in the platform.
Cloud, APIs, and Compliance for Carriers Your Size
Cloud-native setup beats a legacy system overhaul for three practical reasons: faster deployment, lower infrastructure overhead, and cleaner regulatory update cycles when state requirements shift. SaaS insurance solutions cut server maintenance entirely and let your team access the system from anywhere, which matters when IAs are handling field assignments remotely. According to a 2026 insurance software market forecast, cloud-native deployment now accounts for over 65% of insurance software revenue, and the gap with on-premises keeps widening. ScienceSoft’s Q2 2026 analysis finds that 67% of insurers and MGAs plan to increase AI spending over the next 12 to 24 months, which means vendor pricing will likely climb, so it’s worth locking in flexible contract terms now.
TMS and accounting system connections
Bi-directional API connections to your TMS and accounting platform are foundational, not a bonus feature, especially since smaller carriers often run non-standard or legacy financial systems already. A well-documented REST API handles most connection requirements, but carriers with highly customized ERP configurations should budget extra time, typically two to six weeks, and get that timeline in writing before signing anything.
Data security and regulatory requirements
Insurance compliance for claims platforms requires, at minimum, SOC 2 Type II certification and alignment with state insurance department data security rules. Requirements vary by state and line of business, and HIPAA applies wherever workers’ comp or health-adjacent lines are in scope. Verify a vendor’s current certification status directly and ask for the most recent audit report rather than relying on a marketing summary. VCA Software’s SOC 2 Type II certification, completed in May 2026 by independent auditor Prescient Assurance, confirms that its controls operate consistently over time.
Deploying and Supporting Your Platform
Cloud-native go-lives typically run 60 to 120 days. Configurations requiring legacy data migration can stretch to six months or longer. Ask vendors to define timelines contractually rather than just referencing them in demos. Risk & Insurance’s analysis of digital distribution partnerships consistently shows that vendors who commit to timelines in writing deliver faster go-lives than those who treat them as estimates. Per Verified Market Research’s claims processing market data, legacy debt affects over 53% of insurers adopting new software, so it’s worth planning for rather than hoping around. Negotiate data-portability clauses and contract exit terms before signing, since vendor lock-in is harder to undo than it is to prevent.
Dual-entry periods and how to set a deadline
Running old and new systems in parallel is often necessary during go-live, and it’s exhausting for the team. Set an internal cutover date (six to eight weeks is typical) so the transition has a clear endpoint rather than running indefinitely.
Training that doesn’t derail your operation
Role-specific training sessions outperform all-hands sessions every time. Adjusters need to get functional fast, not comprehensively trained on every feature at once. A solid benchmark: if an adjuster can’t open a file, set a reserve, and pull a status report within two hours, either the training design or the system itself has a problem. Long training cycles usually signal a platform that wasn’t built around real workflows.
What partnership looks like after go-live
Long-term partnerships like PIB’s renewal with VCA, a 15-year relationship renewed for another five years, reflect what sustained operational support looks like. Unity Claims cut average claim processing time from 45 minutes to 10 minutes per claim, a 78% reduction, using VCA’s tailored automations. Western Financial Group’s seven-year renewal, covering both delegated authority programs and complex advocacy work, shows how a platform can scale with an organization’s growth.
Pricing and Total Cost of Ownership
The claims management software market was valued at $6.8 billion in 2025 and is projected to hit $16.2 billion by 2034, per DataIntelo, so vendor pricing will keep moving. Subscription structures keep costs tied to actual claim load rather than a forecast made at contract signing, which is why they tend to scale more predictably for mid-size carriers than a large upfront license fee. Per AI in insurance statistics from AllAboutAI, AI capabilities are now a standard expectation inside claims platforms. You’re paying for them whether they’re itemized or not, so it’s worth knowing what’s in the base subscription versus what triggers an add-on fee.
Licensing models for carriers at different scales
| Pricing Model | Best For | Typical Cost Structure |
|---|---|---|
| Per-claim | Low-volume, variable load carriers | Scales with activity; no fixed overhead |
| Per-seat | Stable team size, high claim volume | Predictable monthly cost |
| Tiered volume bands | Mid-size carriers with growth plans | Price steps at defined claim thresholds |
| Enterprise license | Large carriers with dedicated IT | Upfront fee; customization billed separately |
What connections and customization really cost
Connecting to a standard accounting system via a published API typically runs $5,000 to $25,000 one-time. Custom bordereaux reports run $4,000 or more per report. Data migration from a legacy system runs $15,000 to $100,000 or more depending on data quality and volume. Get line-item quotes for each. Current P&C industry data shows that carriers running fewer than five core platforms spend 12% to 18% less on total technology cost than those running 12 or more fragmented point solutions.
Hidden expenses and how to budget honestly
Start with your current IT and staffing costs for claims operations, then add connection, data migration, training, and first-year support costs on top. Compare that full total against subscription tiers rather than headline license numbers. An independent software comparison of the top claims platforms shows that mid-market carriers consistently underestimate year-two costs when they don’t account for customization growth and rising user counts. Carriers processing 100,000 or more claims annually typically see returns within 18 to 24 months.
How VCA Software Fits Into This Selection Process
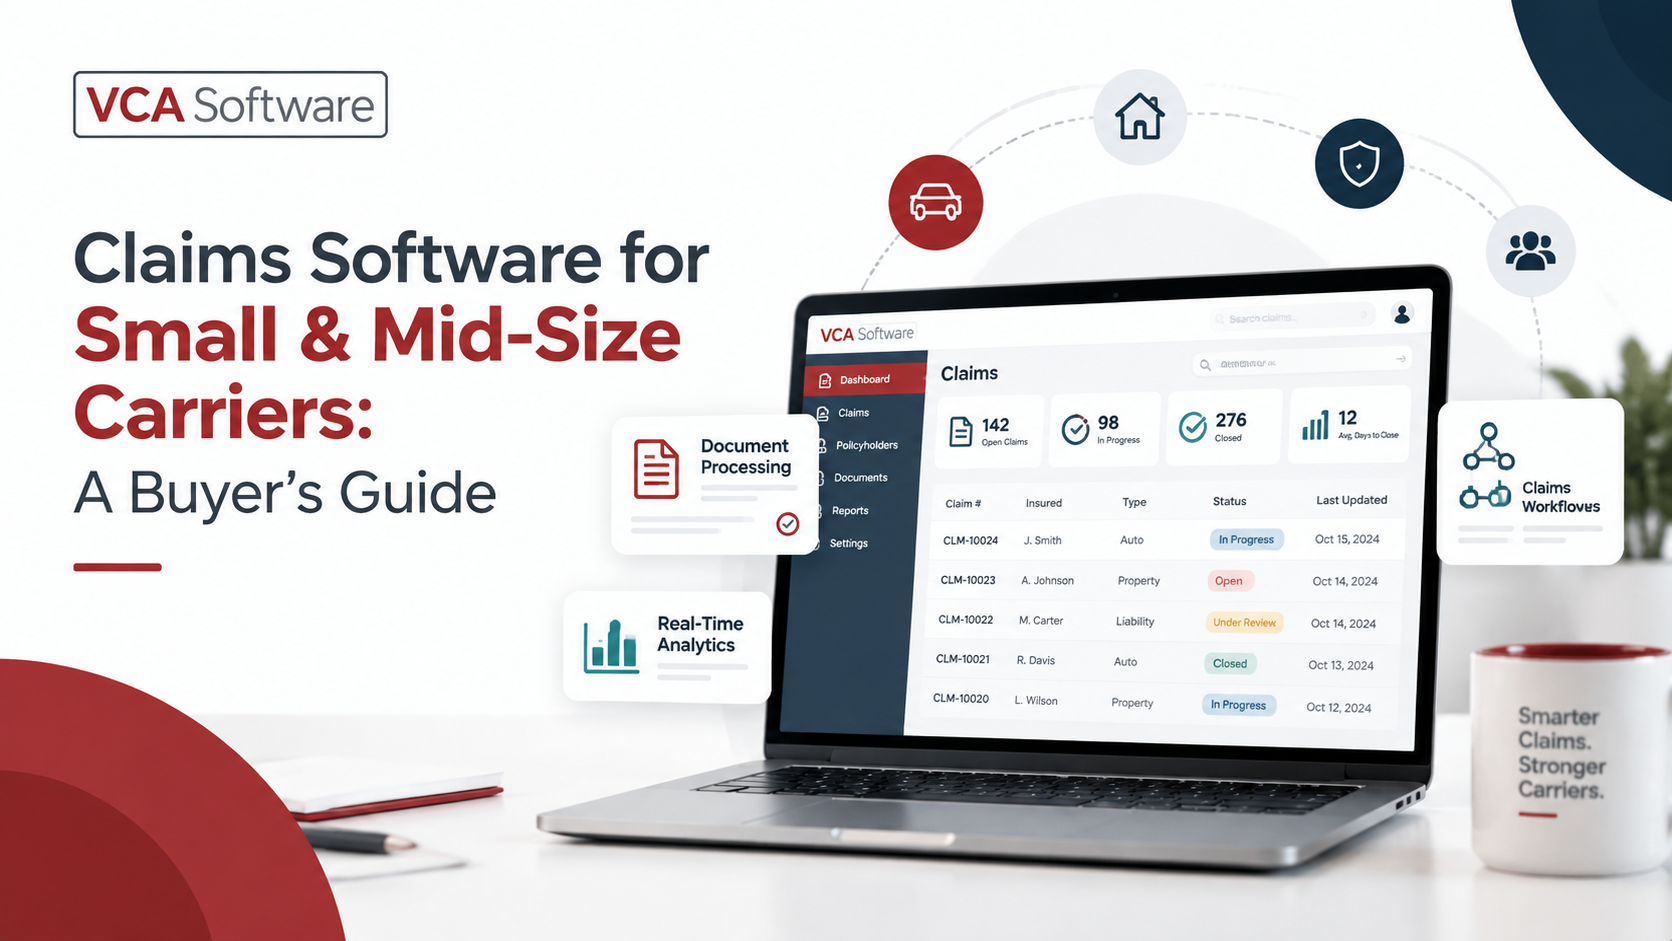
VCA Software was built around the idea that software should fit real workflows. Founded in 1998 and now serving clients in over 15 countries, VCA works with carriers, TPAs, IA firms, MGAs, captives, and self-insured entities through a SaaS platform configured around how each client actually works, from FNOL through bordereaux.
The claims engine handles intake, assignment, reserve tracking, recovery management, and Lloyd’s-compliant reporting in a single platform. VCA was the first claims management software to build Lloyd’s compliance in natively, removing a common connection burden for London-market participants. Optional modules (ClaimPay for digital payments, VCA Insights for analytics dashboards) add capability without forcing every client to pay for what they don’t need yet.
For carriers evaluating timelines: Premier clients go live in as little as two to three weeks, and most file handlers are productive within two hours of training. VCA’s best P&C software comparison ranking reflects verified user ratings of 4.9 on Capterra, earned through operational results.
Over-customization is a real risk, and VCA will flag it to a client before they over-build. That’s part of the partnership.
Conclusion
Claims software for small & mid-size carriers touches combined ratio, policyholder retention, and regulatory standing, not just IT infrastructure. Choose a platform based on the work your claims team actually does, not the features a vendor leads with in a demo. Cloud-native deployment, rules-based automation, native compliance, and transparent pricing are what separate platforms worth evaluating from those worth skipping. The insurance technology trends shaping 2026 point clearly toward platforms that move claims forward rather than systems that merely record them. Per Ivans’ 2025 insurtech trend analysis, carriers that pair underwriting discipline with modern claims technology consistently outperform those that treat the two as separate investments.